Do I Need a 20% Down Payment to Buy a House?
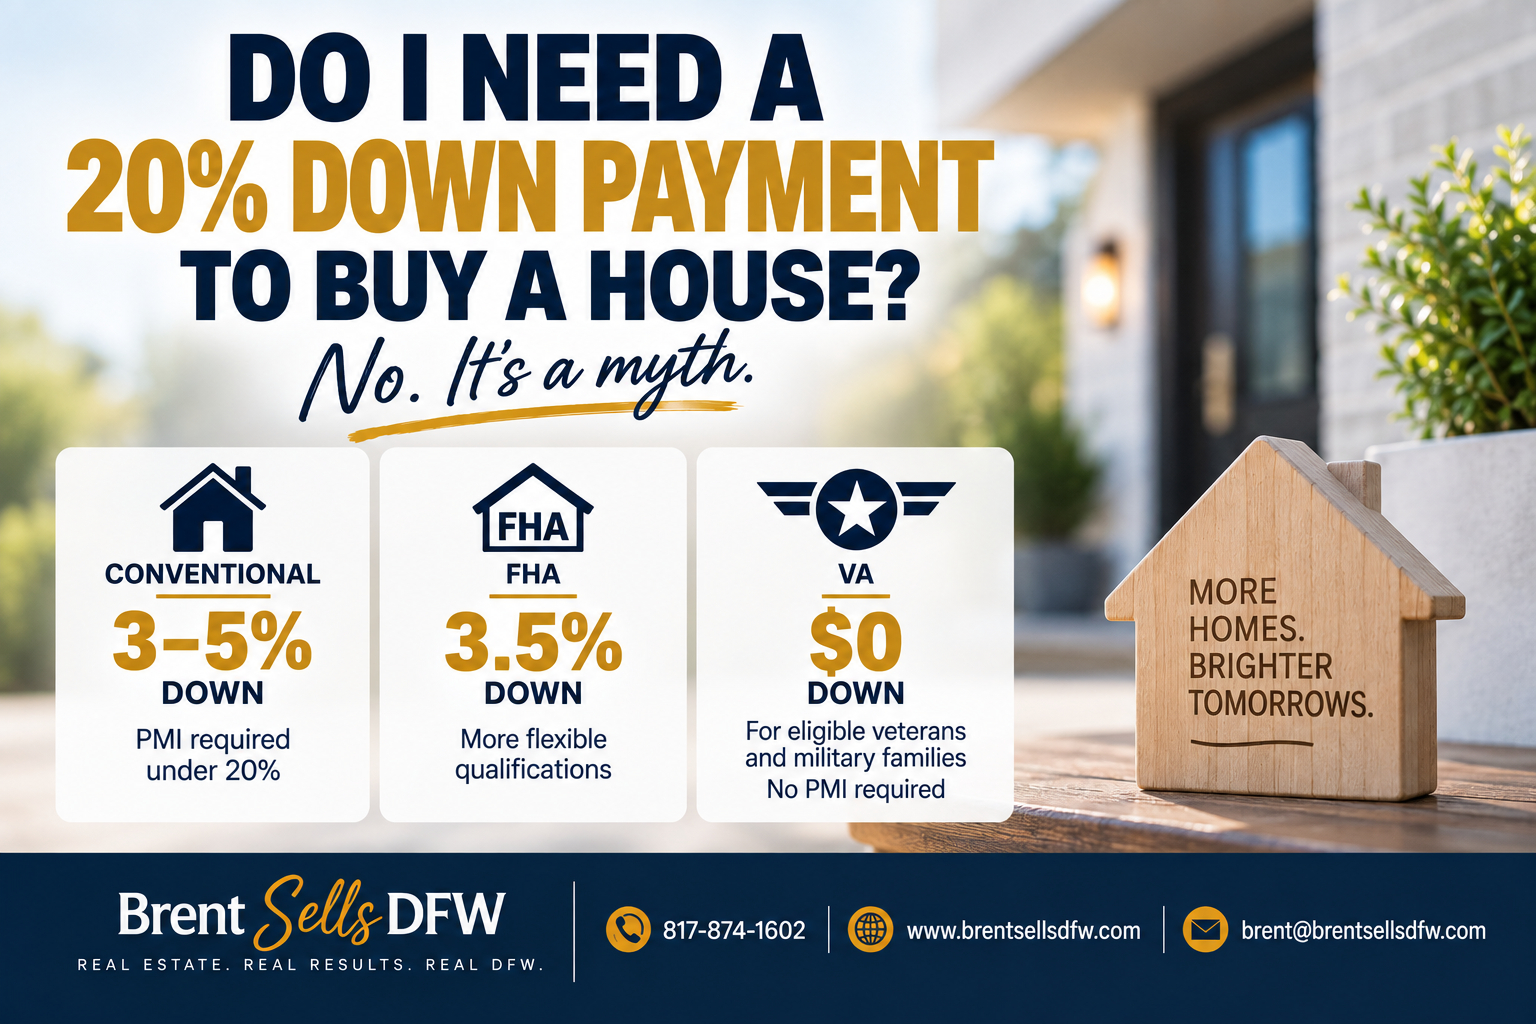
No — 20% down is a myth that keeps a lot of ready buyers on the sidelines longer than they need to be. Conventional loans can go as low as 3–5% down, FHA loans start at 3.5%, and VA loans allow $0 down for eligible veterans and military families. The trade-off for going lower is PMI (private mortgage insurance) on conventional loans until you build enough equity — but that's often a smaller monthly cost than another year of rising prices and rent.
This is one of the most persistent myths in real estate, and it stops more qualified buyers from starting their search than almost anything else. Here's the actual breakdown by loan type.
Conventional Loans: As Low as 3–5% Down
Most first-time buyers qualify for conventional loans with as little as 3% down (5% for some programs or non-first-time buyers). Under 20% down triggers PMI — an added monthly cost that protects the lender, not you — but PMI drops off automatically once you reach 20% equity, either through payments or appreciation.
FHA Loans: 3.5% Down
FHA loans are backed by the federal government and allow down payments as low as 3.5% with credit scores of 580 or higher. FHA also allows more flexibility on debt-to-income ratios than conventional loans, which makes it a strong option if your credit is still being built.
VA Loans: $0 Down
Eligible veterans, active-duty service members, and certain military spouses can buy with zero down through a VA loan — no PMI required, either. If you or your spouse served, this is often the strongest loan option available, full stop.
So Why Does the "20% Rule" Still Exist?
Two real reasons, and one myth:
Real: PMI. Putting down less than 20% on a conventional loan does mean paying PMI until you hit that equity threshold. It's not free, but it's also often far less than people assume — commonly $50–$150/month on a typical DFW home price.
Real: Competitive offers. In a multiple-offer situation, a larger down payment can occasionally make an offer look stronger to a seller. But in today's more balanced DFW market, this matters far less than it did in 2021–2022.
Myth: That 20% is required to qualify at all. It never has been for most loan types — this idea just persists because it used to be the norm decades ago.
What This Actually Means for Your Timeline
If you've been waiting to save 20% before starting your search, run the real math first. Saving an extra $40,000–$60,000 to hit 20% on a $400,000 home could easily take years longer than saving 3–5% — years during which home prices and rates can move in either direction. For a lot of buyers, the smarter move is buying sooner with a smaller down payment and refinancing or paying down PMI later, rather than renting while chasing a 20% target that keeps moving with the market.
Bottom Line
You don't need 20% down to buy in DFW — you need to know which loan program actually fits your situation, because the "right" down payment is different for a first-time buyer, a veteran, and someone with a bigger cash reserve. The only way to know your real number is to run it with a lender.
Curious what you'd actually qualify for? A 10-minute conversation with a lender will tell you your real number — not the internet's outdated rule of thumb. The buyers who find out now are the ones already shopping while everyone else is still saving for a number they never needed to hit.
Brent Reiter, REALTOR® | Brent Sells DFW
Real Estate. Real Results. Real DFW.
817-874-1602 | brent@brentsellsdfw.com
Serving Dallas-Fort Worth.
Sources & Citations
Have Questions? Let's Talk.
Fill out the form below and I'll get back to you shortly. No pressure, just honest guidance.