Should I Sell My Current Home Before Buying a New One?
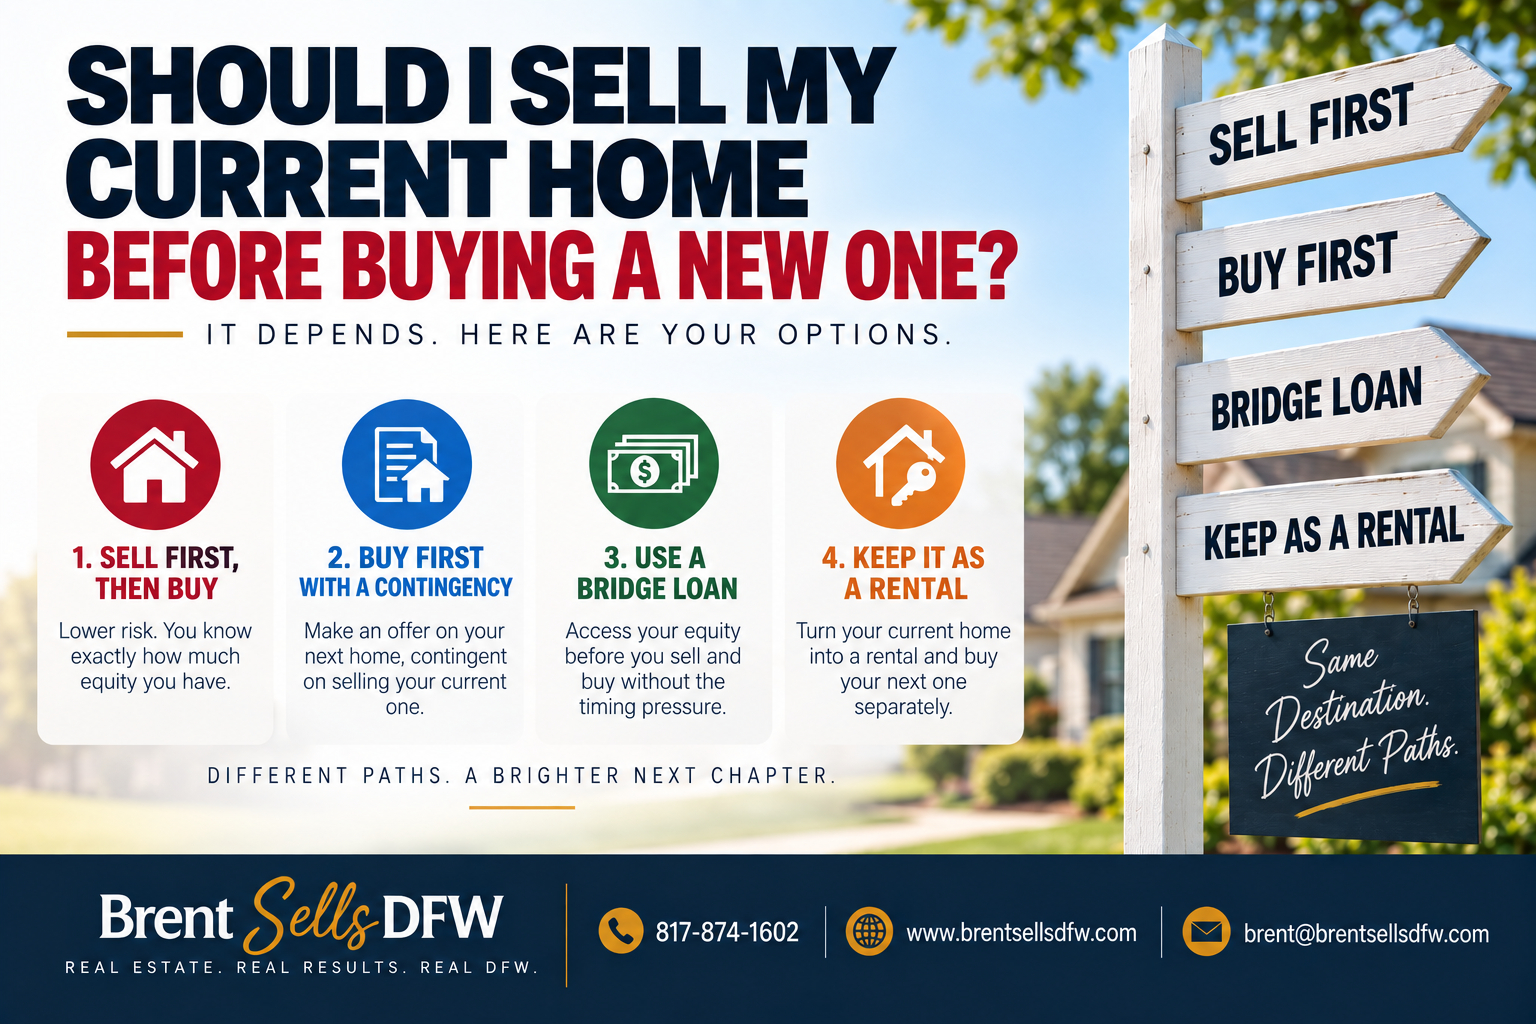
There's no universal right order. You can sell first and then buy, buy with a home-sale contingency, use a bridge loan to access equity before you sell, or potentially keep your current home as a rental. The best approach depends on how much equity you have, your cash reserves, financing qualifications, tolerance for carrying two properties, and current market conditions.
This is one of the most common questions homeowners face when they're ready to move up, downsize or relocate — and there isn't one strategy that works for everyone. The goal isn't simply to decide whether you should sell first or buy first. It's to figure out which approach gives you the best combination of financial flexibility, negotiating power and manageable risk.
Here are the four main options.
Option 1: Sell First, Then Buy
This is generally the lower-risk path financially. Selling first tells you exactly how much equity you have available for your next purchase, and it reduces the risk of carrying two mortgage payments at the same time.
The trade-off is timing. If you haven't found your next home by the time your current home closes, you may need temporary housing, a short-term rental, or potentially negotiate a leaseback with your buyer.
Best suited for: Homeowners who need the equity from their current home to purchase the next one or who aren't comfortable carrying two properties simultaneously.
Option 2: Buy First With a Home-Sale Contingency
A home-sale contingency allows you to make an offer on your next property that's dependent on successfully selling your current home. That can help solve the question of, 'Where do we live between houses?'
But there's a trade-off. A seller may consider an offer with a home-sale contingency less certain than an offer from a buyer who doesn't need to sell another property first. Home-sale contingencies may be easier for sellers to consider when buyers have more negotiating leverage and homes are taking longer to sell.
Best suited for: Homeowners who need their existing home to sell but want to secure their next property before completing that sale.
Option 3: Use a Bridge Loan
A bridge loan can allow you to access some of the equity in your current home before it sells, potentially providing funds toward the purchase of your next home without waiting for the first closing. You may temporarily carry obligations on both properties, but a bridge loan can reduce the pressure of trying to coordinate two closings perfectly.
The trade-off is cost and qualification. Bridge financing may involve additional interest, fees and lending requirements. Availability, qualification requirements, rates, fees and repayment terms vary by lender. This strategy needs to be evaluated alongside a lender based on your income, equity, credit and overall financial position.
Best suited for: Homeowners with substantial equity who can qualify for the financing and want greater flexibility in coordinating the two transactions.
Option 4: Keep Your Current Home as a Rental
Selling isn't your only option. Some homeowners keep their current property and convert it into a rental while purchasing another home. Depending on the loan program and lender requirements, some of the property's qualifying rental income may be considered when financing the next home.
But simply being able to rent the property for more than the mortgage payment doesn't automatically make it a good investment. You also need to consider property taxes, homeowners and landlord insurance, maintenance and repairs, vacancy, property management, HOA expenses (if applicable), and future capital expenses. And, of course, becoming a landlord comes with responsibilities that you don't have when you simply sell the property.
Best suited for: Homeowners who can qualify for the next home without selling and whose existing property makes financial sense as a rental.
How Do You Actually Decide?
Before deciding which direction to take, answer four questions:
- How much equity do you have, and do you need it for the next purchase?
- Can you qualify for—and comfortably carry—both properties if there's an overlap?
- How quickly is your current home realistically likely to sell?
- If you're considering keeping it, does the property actually make sense as a rental after mortgage, taxes, insurance, maintenance, vacancy and management costs?
Those answers can quickly eliminate options that don't make financial sense and help identify the strategies worth exploring further. This is why simply following a rule like "always sell first" or "always buy before you sell" isn't particularly useful. Your equity, financing and local market conditions matter.
Bottom Line
Selling first, buying with a contingency, using bridge financing, or keeping your current home as a rental can all be legitimate strategies. The right approach depends on your equity, cash reserves, financing qualifications, tolerance for risk and the market conditions affecting both your current home and the one you want to buy. The important thing is to run the scenarios before making the decision rather than discovering halfway through the process that your original plan doesn't work.
Not Sure Which Path Fits Your Situation?
Let's start by looking at your home's likely market value, estimated equity, your next-home price range and current market conditions. From there, we can determine which options are worth exploring and, when financing is involved, coordinate with a lender to run the actual loan scenarios. You don't have to sell your home just to find out what your options are.
Talk Through Your OptionsBrent Reiter, REALTOR® | Brent Sells DFW
817-874-1602 | brent@brentsellsdfw.com
Real Estate. Real Results. Real DFW.
Serving Dallas-Fort Worth.
Have Questions? Let's Talk.
Fill out the form below and I'll get back to you shortly. No pressure, just honest guidance.